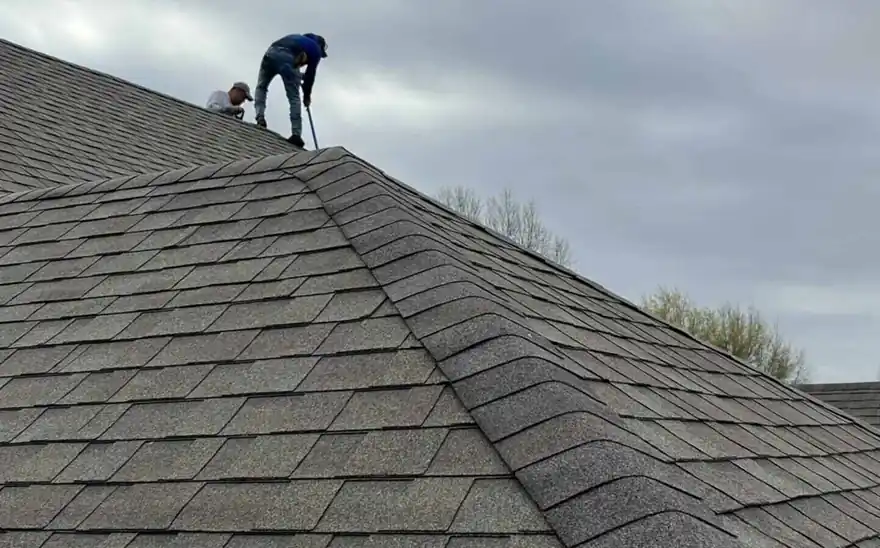
Request a free inspection
An inspector walks the roof and photographs what he finds. It usually takes 30 minutes to an hour, you don't have to be home, and you get a written assessment either way.
Insurance restoration, Tyler and East Texas
Whether it is your first claim or your fifth, the process is usually confusing and frustrating, and after a major storm there are contractors who take advantage of distressed homeowners. At Steele a project manager stays with you through the whole claim, so ask them anything.
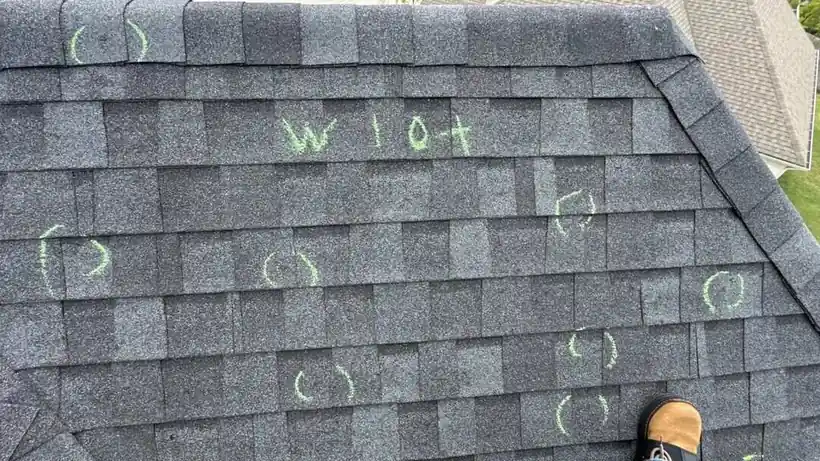
This is Steele's insurance restoration process. Scroll sideways, one stop at a time.
An inspector walks the roof and photographs what he finds. It usually takes 30 minutes to an hour, you don't have to be home, and you get a written assessment either way.
You open the claim with your insurance company. You are not required to collect three estimates, and you can choose whichever contractor you want to do the work.
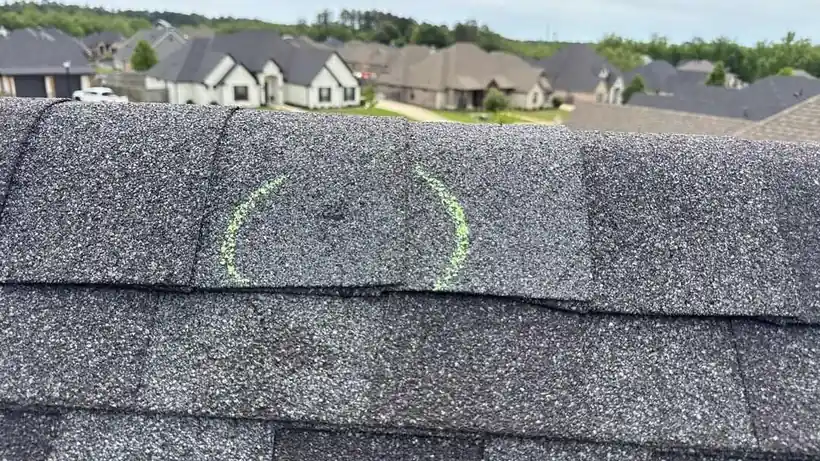
Steele Roofing gives your insurance company its damage assessment and answers any questions about the recommended repairs, so the adjuster and the contractor are looking at the same roof.
Once the final scope is authorized, Steele completes it at the price your insurance company or adjuster authorized. Generally, your only out-of-pocket expense is your deductible.
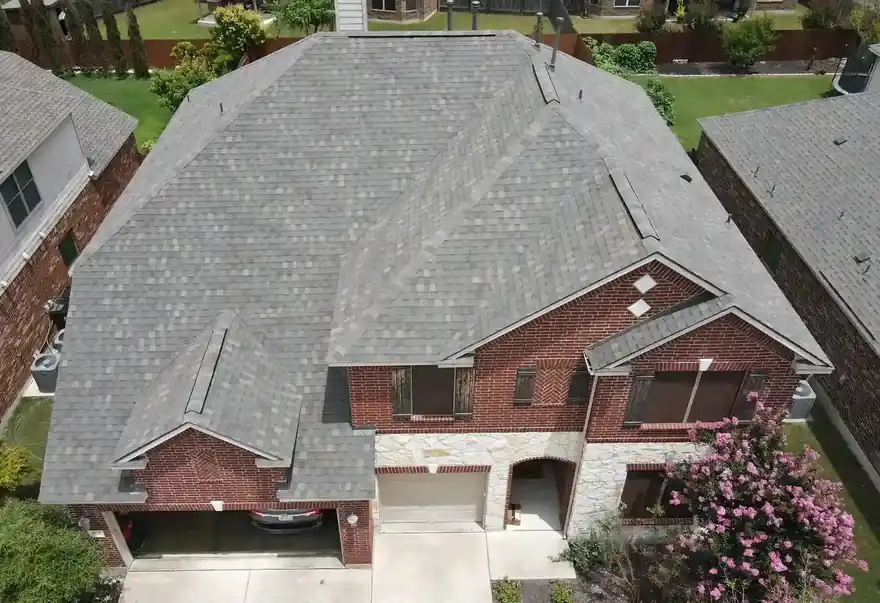
The crew builds the approved scope. Your project manager handles the change order if the scope shifts, and walks you through the insurance check from start to finish.
Storm just came through? Start with a free inspection, or read how the crew handles storm restoration and emergency tarping.
Every policy is different. For questions about your own coverage, talk to your project manager and your insurance company.
The check
How the check is handled varies by circumstances. Sometimes, if your mortgage company is a local bank, certain branches can endorse the check for you. Other times it may be necessary to mail the check to the mortgage company.
Either way, your project manager guides you through the steps.
Three estimates
No. You are allowed to choose whichever contractor you want. Steele Roofing gives your insurance company its damage assessment and answers any questions about the recommended repairs.
Generally your only out-of-pocket expense is your insurance deductible. Steele completes the final approved scope at the price authorized by the insurance company or adjuster.
Per insurance proceeds
Chances are Steele uses the same estimating software and pricing as your insurance company. Once the final scope is authorized, the work is performed at the insurance company's pricing, which streamlines the repair process.
Change orders
Your adjuster first authorizes a scope of work. That estimate can change in scope and cost during construction because of a mis-measurement of materials, additional damage found once the work begins, or other unforeseen issues.
When that happens your project manager submits a change order to the insurance company. It is standard procedure and insurers expect it. Any extra funds released are part of the job cost and are due to Steele Roofing like any other insurance payment.
Denied claims
You can request a re-adjustment and have your project manager present when the adjuster reassesses the damage, so all claim-related damage is pointed out.
If the claim is denied a second time, look into the appeal or grievance policy of your insurance company, or Steele can refer you to other industry professionals who may be able to help you work with your insurer. Your construction agreement with Steele is contingent on insurance approval and no work is done without it, so you are not liable for payment in that case.
Rates
It is a huge concern, and Steele's honest answer is this: when there is widespread weather-related damage, everybody's insurance cost goes up. If your area or zip code was an expensive one for the insurer because of an act of God, you are affected whether you file or not.
Remember that you pay, heavily, to insure your home for problems just like this.
Mortgage company
Your mortgage company often appears on the insurance proceeds because it has a vested interest in the condition of your property. It wants the required work completed, and it will often send out an inspector to check progress or completion of the job.
The inspection is free, you get a written assessment either way, and keeping a roof in shape between storms is what the Steele Shield plan is for.